
Highlights:
IT consulting stocks have been crushed of late. A basket of five major names is down more than 35% YTD.
Optimism around generative artificial intelligence seems to be the culprit. Weak results across the sector suggest the trend isn’t helping — and may be hurting.
But there’s a logical explanation for industry weakness: belt-tightening across the corporate world. Simply put, the cycle has turned, and most customers aren’t yet ready for genAI projects to change that.
In the meantime, one sector player trades at what look like trough multiples. A change in the cycle suggests gains well past 100%.
We know that organizations across nearly every industry are working feverishly to understand the impact of generative artificial intelligence on their businesses. We know this because they’re telling us so:
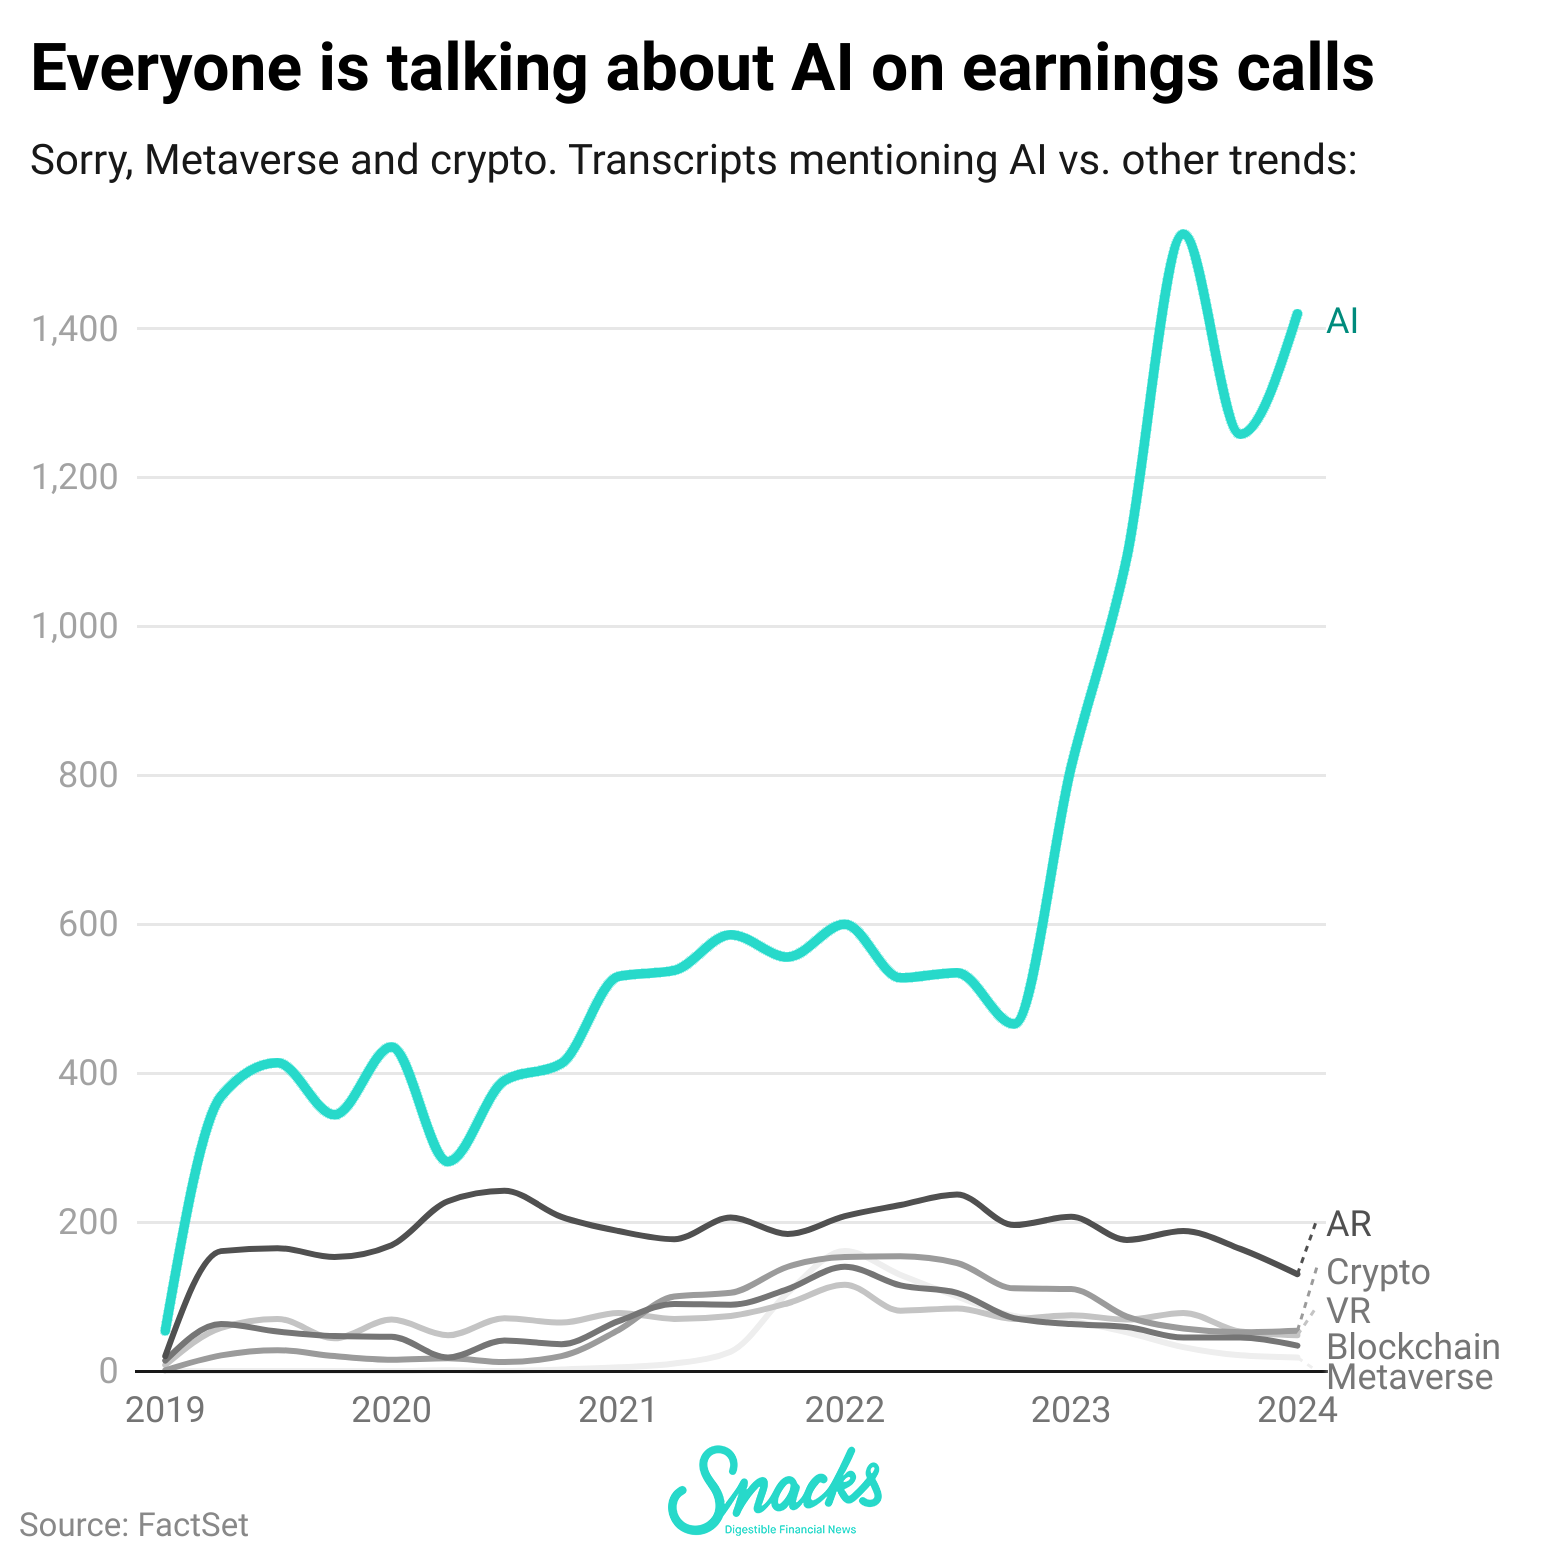
source: Robinhood Snacks1
We also know that most of these organizations have little experience with generative AI. The technology is simply too new. Many companies are now hiring aggressively — and paying well — for workers with experience. But few of those workers have the institutional currency or rank to lead enterprise-wide AI initiatives.
And so there would seem to be an absolutely screaming opportunity for IT consulting firms — among them Perficient PRFT 0.00%↑ — to capitalize on the gap between these organizations’ needs and their in-house talent. Yet that potential opportunity has not materialized, leading the entire sector to underperform (the black line on top is the NASDAQ 100):
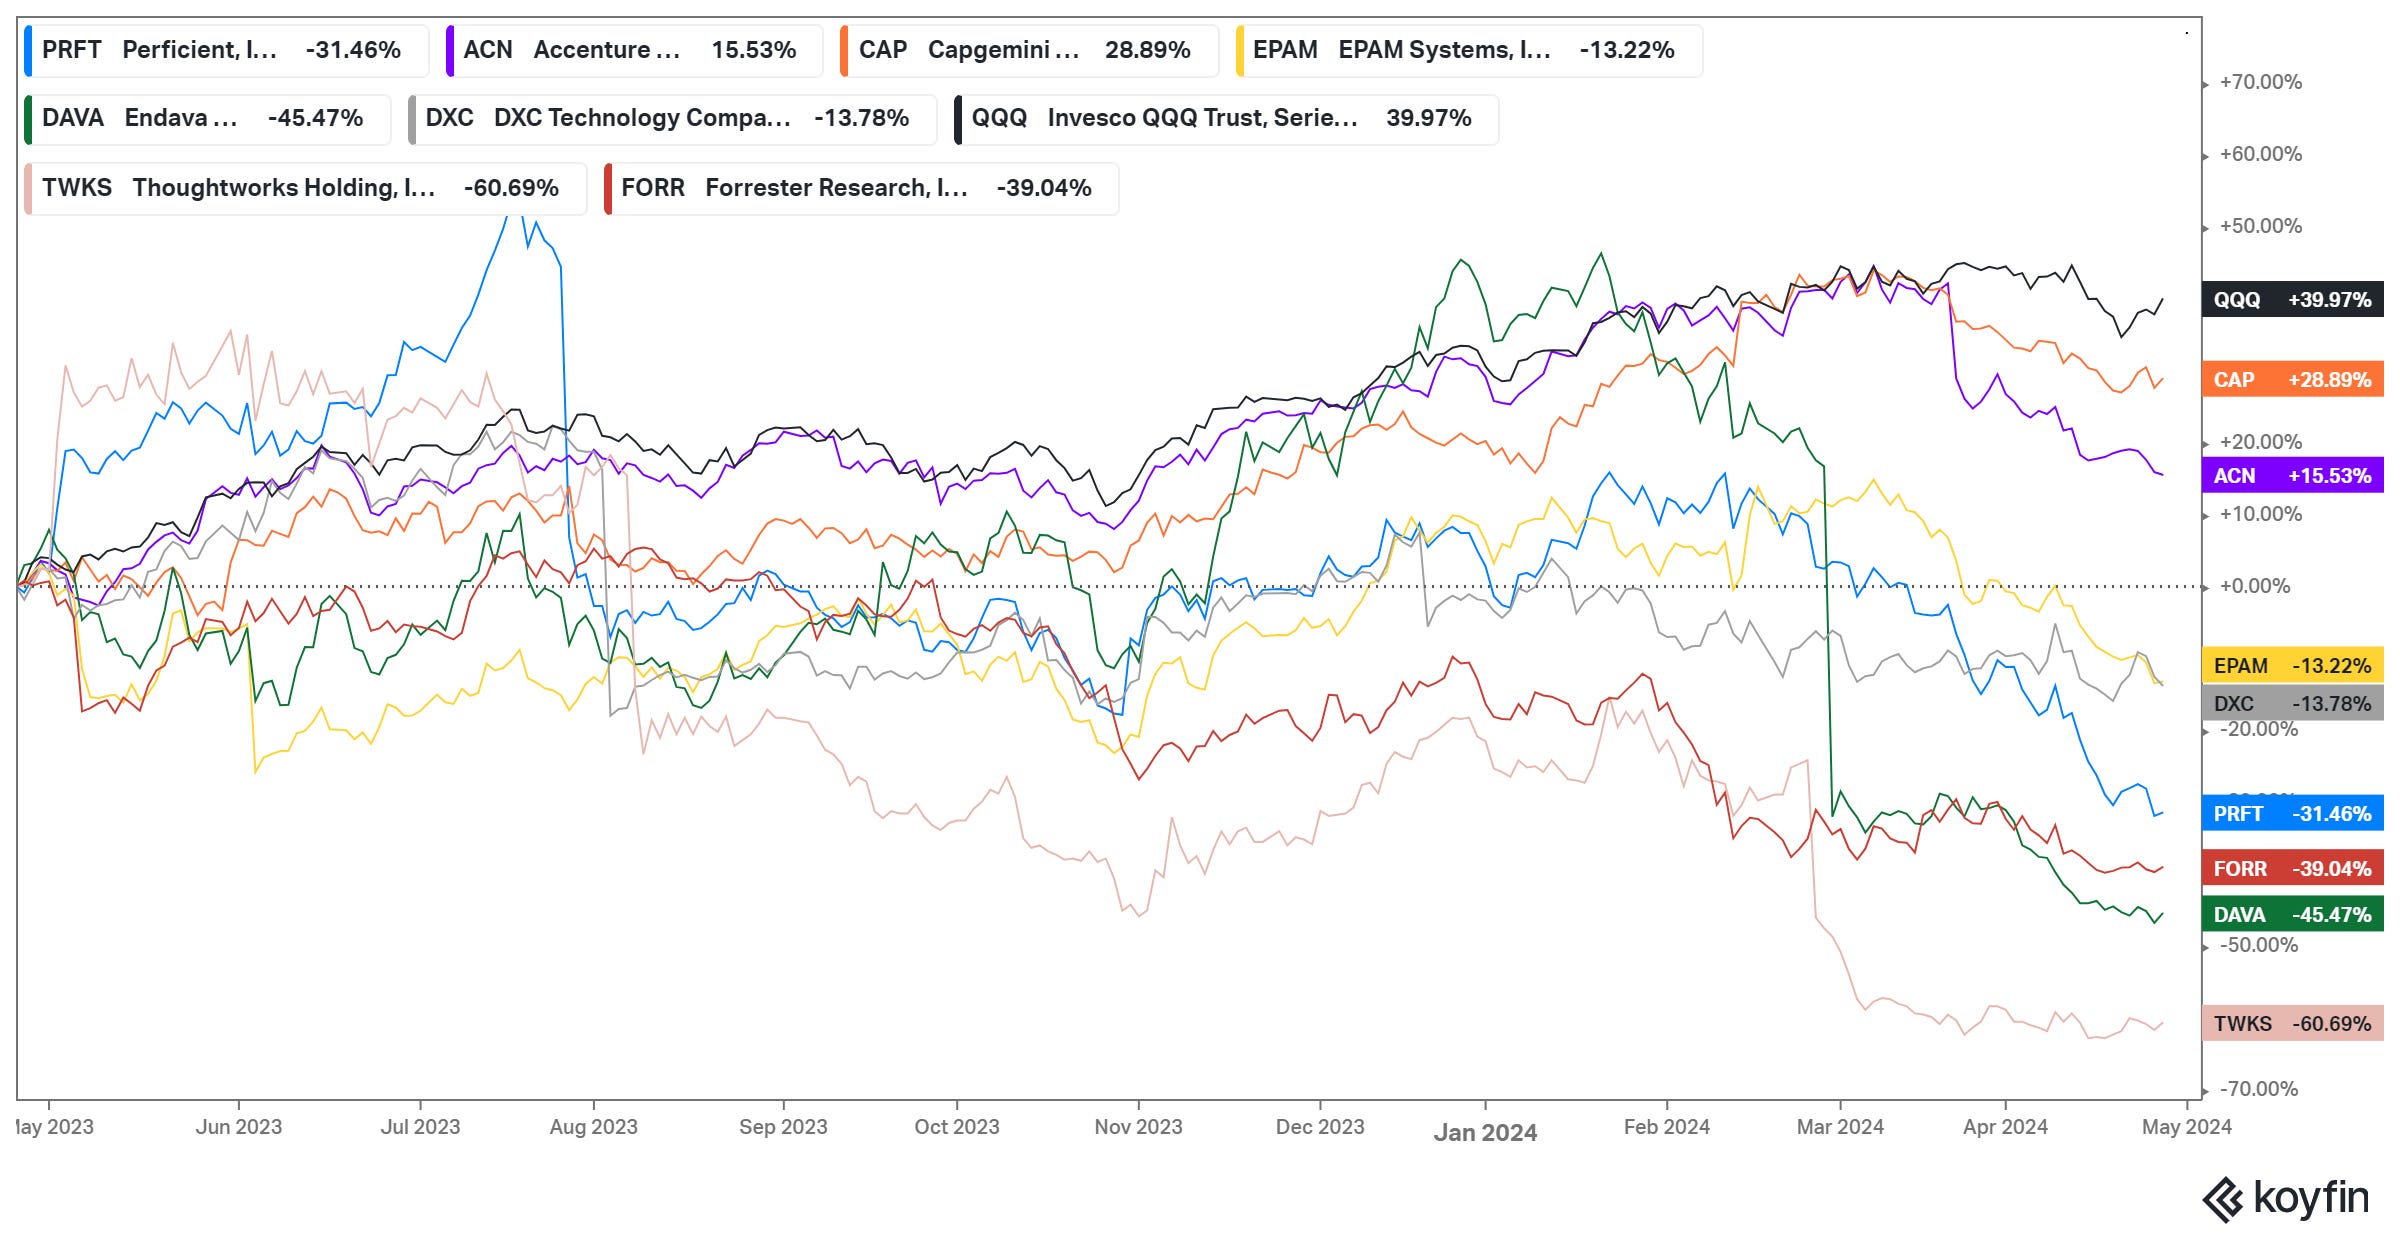
source: Koyfin; one-year chart2
Broadly speaking the more tech-focused the consultancy, the worse its stock has performed. That correlation seems surprising, but it actually makes some sense in the context of recent results, which have been awful. Right now, the entire industry seems to be struggling, and the seemingly logical response by investors has been to sell.
But there is an intriguing argument that the market is completely misreading the situation, and failing to realize that AI itself is to some degree the cause of these recent results. Eventually, that will change. GenAI plus a cyclical reversal sets the table for exceptionally strong growth in the not-too-distant future.
If that argument is correct, nearly all of these names have attractive bull cases — but at the moment, Perficient stock seems to have the strongest one.
source: Office Space meme via RobJoswiak.com
Introducing Perficient
Perficient is a project-based digital consultancy. The firm works with clients — some of the bigger names include Ford F 0.00%↑, Caterpillar CAT 0.00%↑, and Johnson & Johnson JNJ 0.00%↑ — on every aspect of their tech operations, ranging from data analysis to digital marketing to internal app development. The focus, unsurprisingly, generally is on verticals outside of tech, where Perficient consultants can add value and expertise to digital efforts, particularly with newer technologies:
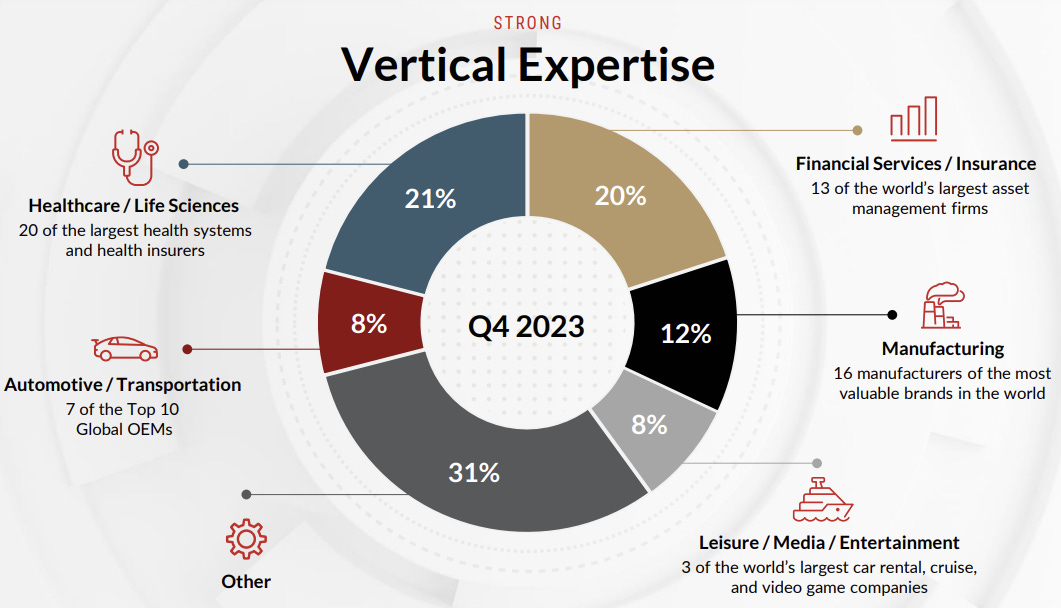
source: Perficient investor presentation
The company was founded in 1998, as a provider of what it called virtual professional services organizations. This entailed basically being an outsourcing partner to software companies; within a few years, the business model changed to the current consulting focus. Steady acquisition activity has been a key part of the strategy, with the firm continually buying smaller shops to bring on both talent and clients. Of course, the rapid technological change of the last 25 years has helped enormously as well, creating a nearly-constant stream of new trends through which non-tech businesses need help managing.
Perficient very much was a creation of the dot-com bubble. The company went public the year after it was founded; at the time of the initial public offering it incredibly had only 19 employees. (It would end the year with 180.) Despite that, PRFT was a reasonably good stock over time, providing 8%-plus annualized returns from its first-day close through the end of 2019.
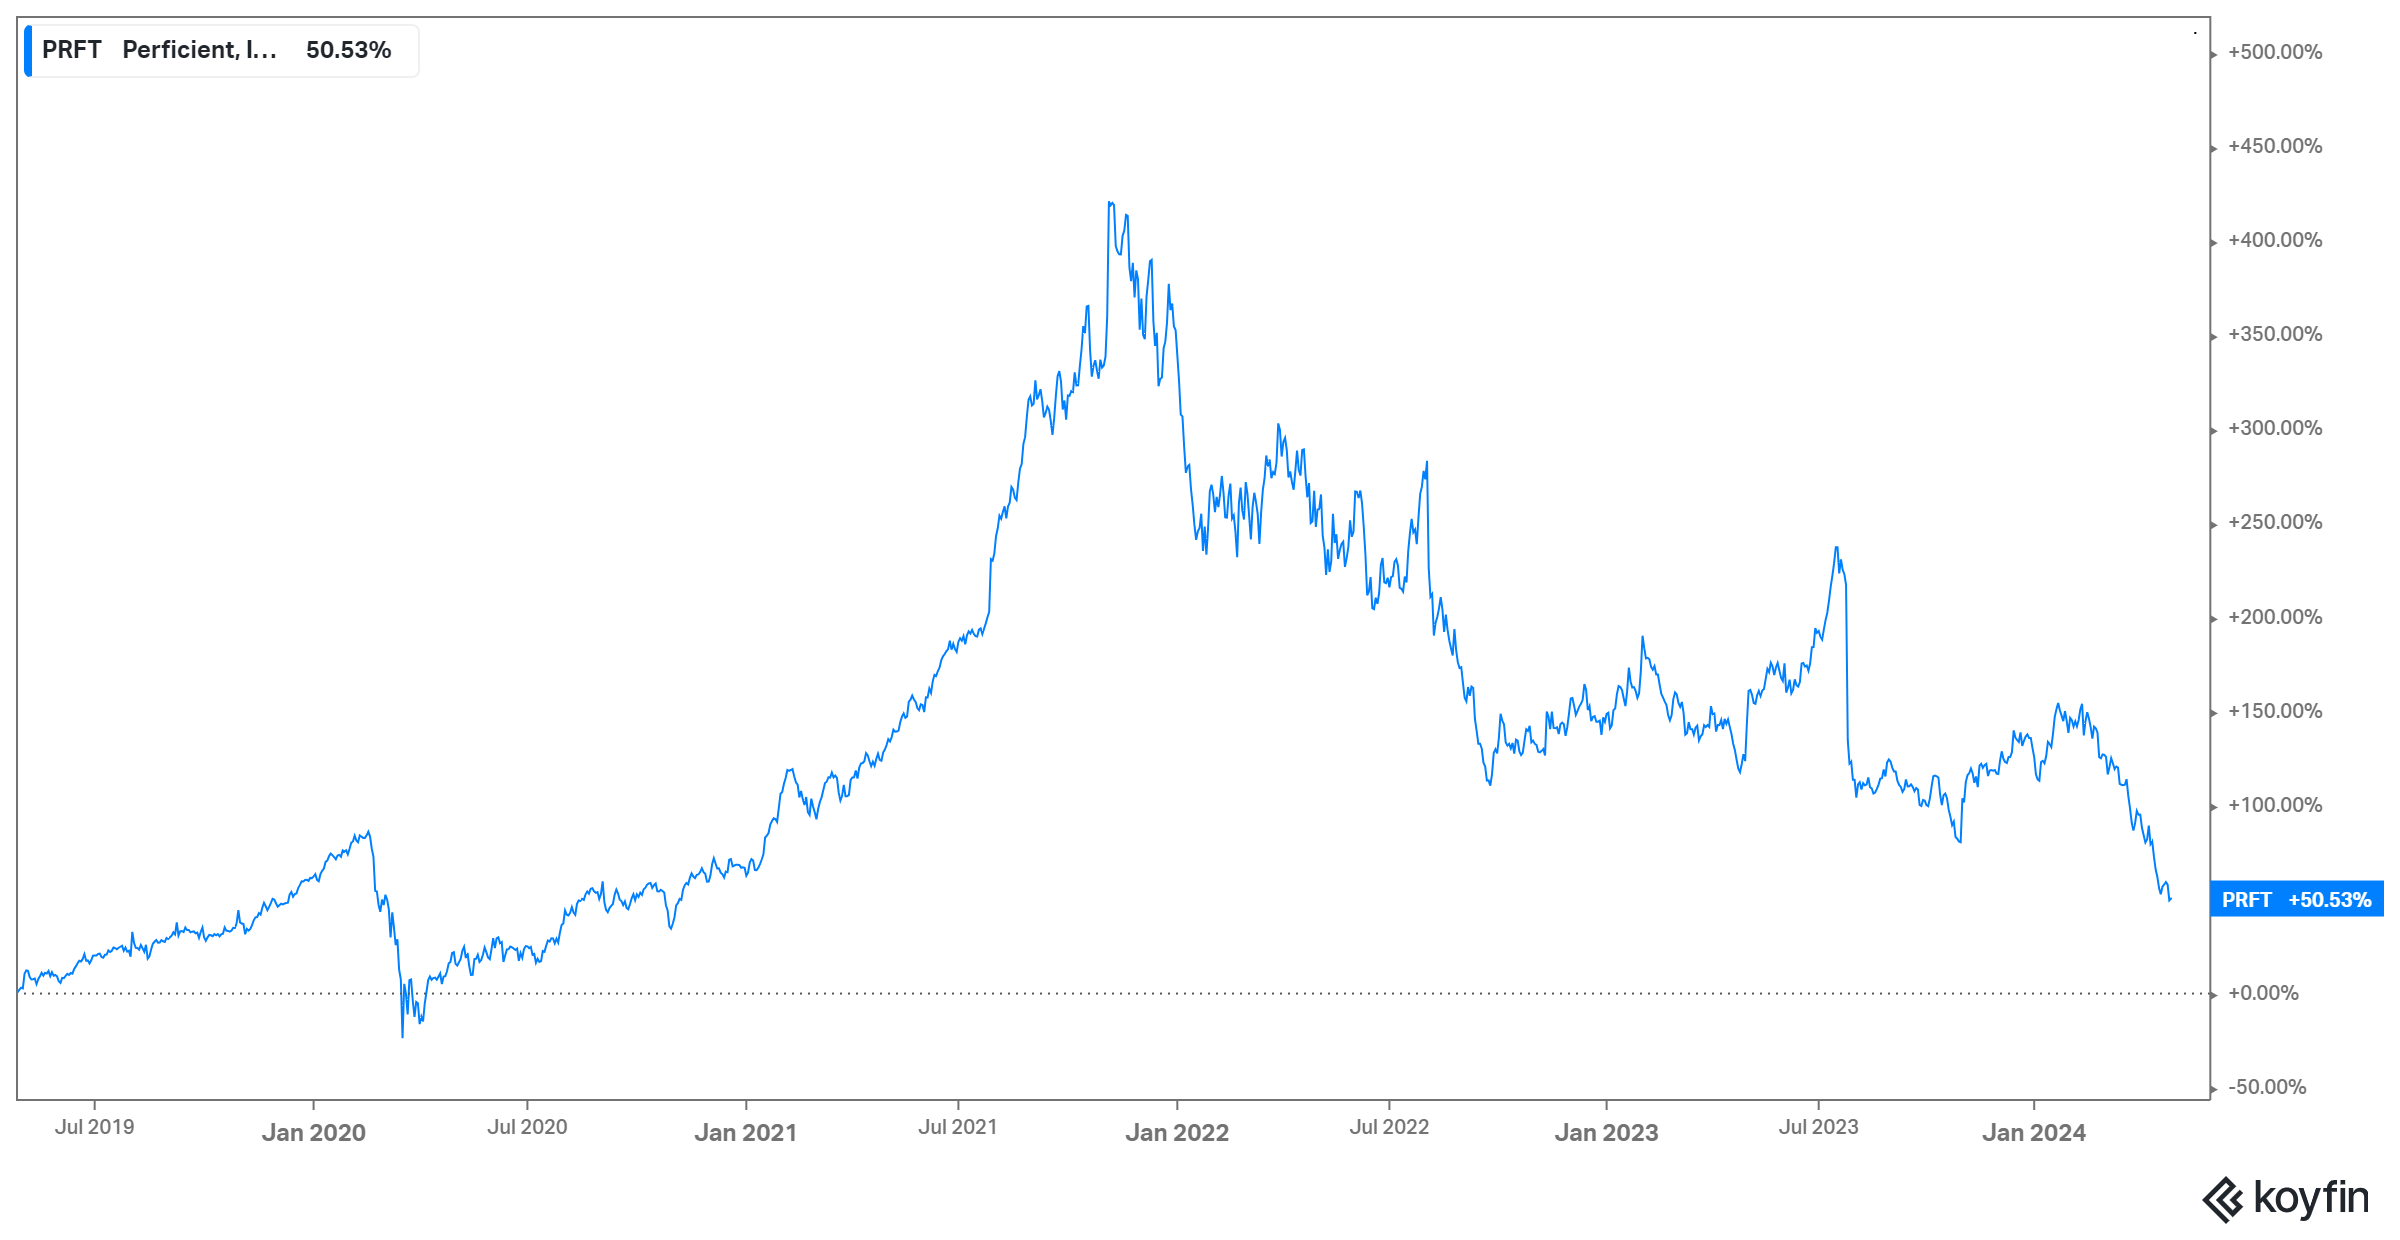
Those returns perhaps don’t sound like much, but of course the July 1999 IPO came less than a year before the tech market peaked. By the end of 2019, PRFT in fact had outperformed the NASDAQ 100, something that few 1999 IPOs can claim (even narrowing the field down to those companies that still exist)3. The optimism, and the outperformance relative to the index, continued through the post-pandemic period, but has reversed sharply of late. PRFT now trades below its level at the end of 2019, with shares down more than 70% from their November 2021 high.
Consultancies Struggle
As the chart above shows, PRFT is not alone in selling off. Across the board, the IT consultancy sector is struggling at the moment.
Accenture ACN 0.00%↑ cut its full-year guidance after fiscal second quarter earnings in March; the firm expects revenue growth of just 1% to 3% in FY24 (ending August). ACN stock is down almost 20% since the release.
The fiscal Q2 report from London-based Endava DAVA 0.00%↑ in late February was even worse. The company’s full-year constant-currency revenue outlook went from 1% to 2.5% growth after Q1 to a 5% to 7% decline three months later. DAVA plunged 42% the next day, is off 53% since earnings and trades at a level not seen since the worst of the pandemic-driven selling in March 2020.
Thoughtworks TWKS 0.00%↑ fell 29% after its Q4 report in February, thanks in large to projections for a second consecutive year with revenue declining double-digits. Forrester Research FORR 0.00%↑ hit a 14-year low this month; it reported a 23% decline in consulting revenue (25% of total revenue) last year. Perficient itself is projecting revenue growth of just 2% to 6% this year on top of a ~flat performance in 2023, and sell-side analysts already have moved to the low end of that range.
The industry right now just looks like a mess. And given that — at least in theory — the group should be benefiting from the huge increase in genAI interest, the negative sentiment toward the space seems logical. After all, if these are the numbers consultancies are posting amid a generational trend, what would business look like without AI demand?
The End Of Consultants
The short-term risk to the group is further earnings weakness. Perficient itself reports Q1 earnings next Monday, May 6, and given an exceptionally ugly chart it’s nerve-wracking to own (or even recommend) shares ahead of that release:
source: Koyfin
Sell-side analysts to some extent are following stock prices down, particularly without a clear catalyst for the sector’s performance to reverse in the next couple of quarters. And so there’s a risk that being long PRFT, or any of its peers, may be correct, but also quite early.
The more credible risk, however, would seem to be that the short-term weakness is a signal from the market of eventual long-term disruption. In a genAI world, consultants may simply go away, replaced by LLM (large language models) that can provide advice of nearly-similar quality at a tiny fraction of the cost.
This is a simple argument to make. But it also appears to be an overly simplistic argument to make, with its weakness highlighted by an analogue from a very different industry.
Back in November 2016, then-President Obama gave an interview to the New Yorker in which he wondered aloud about the effects of technology on societal “cohesion”. Obama pondered a future in which, among other things, “radiologists are losing their jobs to AI.”
As it happened, someone close to me was (and, despite the continuing growth of AI in medicine, remains) a radiologist. I had read the interview, and I asked her if she worried about being displaced. Her response was simple: “No, because if there’s no radiologist there’s no one for the attending physician to blame.”
The same mentality absolutely exists in the corporate world. The idea that a C-suite executive will ask ChatGPT, “how should our company manage our genAI implementation?” is of course fanciful. But even in a world five years from now where the company may have a focused LLM built on internal data, an LLM which may provide advice more specific to the company itself, someone still needs to make the decision.
Consultants have value in the sense of being an outside voice, and of providing trained and (usually) experienced insights. But consultants also provide cover, as Office Space, the movie screenshotted above, so brilliantly demonstrates. In the film, the arrival of consultants is instantly and correctly recognized as signaling a significant workplace reduction; that’s why the consultants are there. In real life, it’s not just layoffs, but process changes, that can be justified as recommended by outside voices.
But of course, the cover can go upward as well. Advice from consultants can provide support for managers as they make recommendations to their higher-ups; that advice means the desired strategy has a basis beyond the opinion of someone not empowered to make the ultimate decision. And, as in the corollary of the radiologist and the attending cited above, consultants provide the potential for face-saving if the plans don’t work.
In all of these cases, the ability to say “well, this is what the consultants think” matters. That ability deflects some responsibility (and in many cases, some personal animus) for potentially unpopular decisions that travel down the organizational chart.
Obviously, consultants do provide some real value; it is helpful to organizations have outside, experienced, and expert voices reviewing processes and aiding in decision-making. But it’s undeniable that the human nature of employees within those organizations also plays a key role in the consistent, large demand for consultants across essentially every industry in existence. To believe that genAI will soon displace consultants requires that human nature be displaced just as quickly. It seems unlikely.
What Is Going On Here?
So if consulting revenues aren’t being pressured by AI, and if the entire sector is down, the obvious question is what has caused Perficient’s revenue to slow so dramatically.
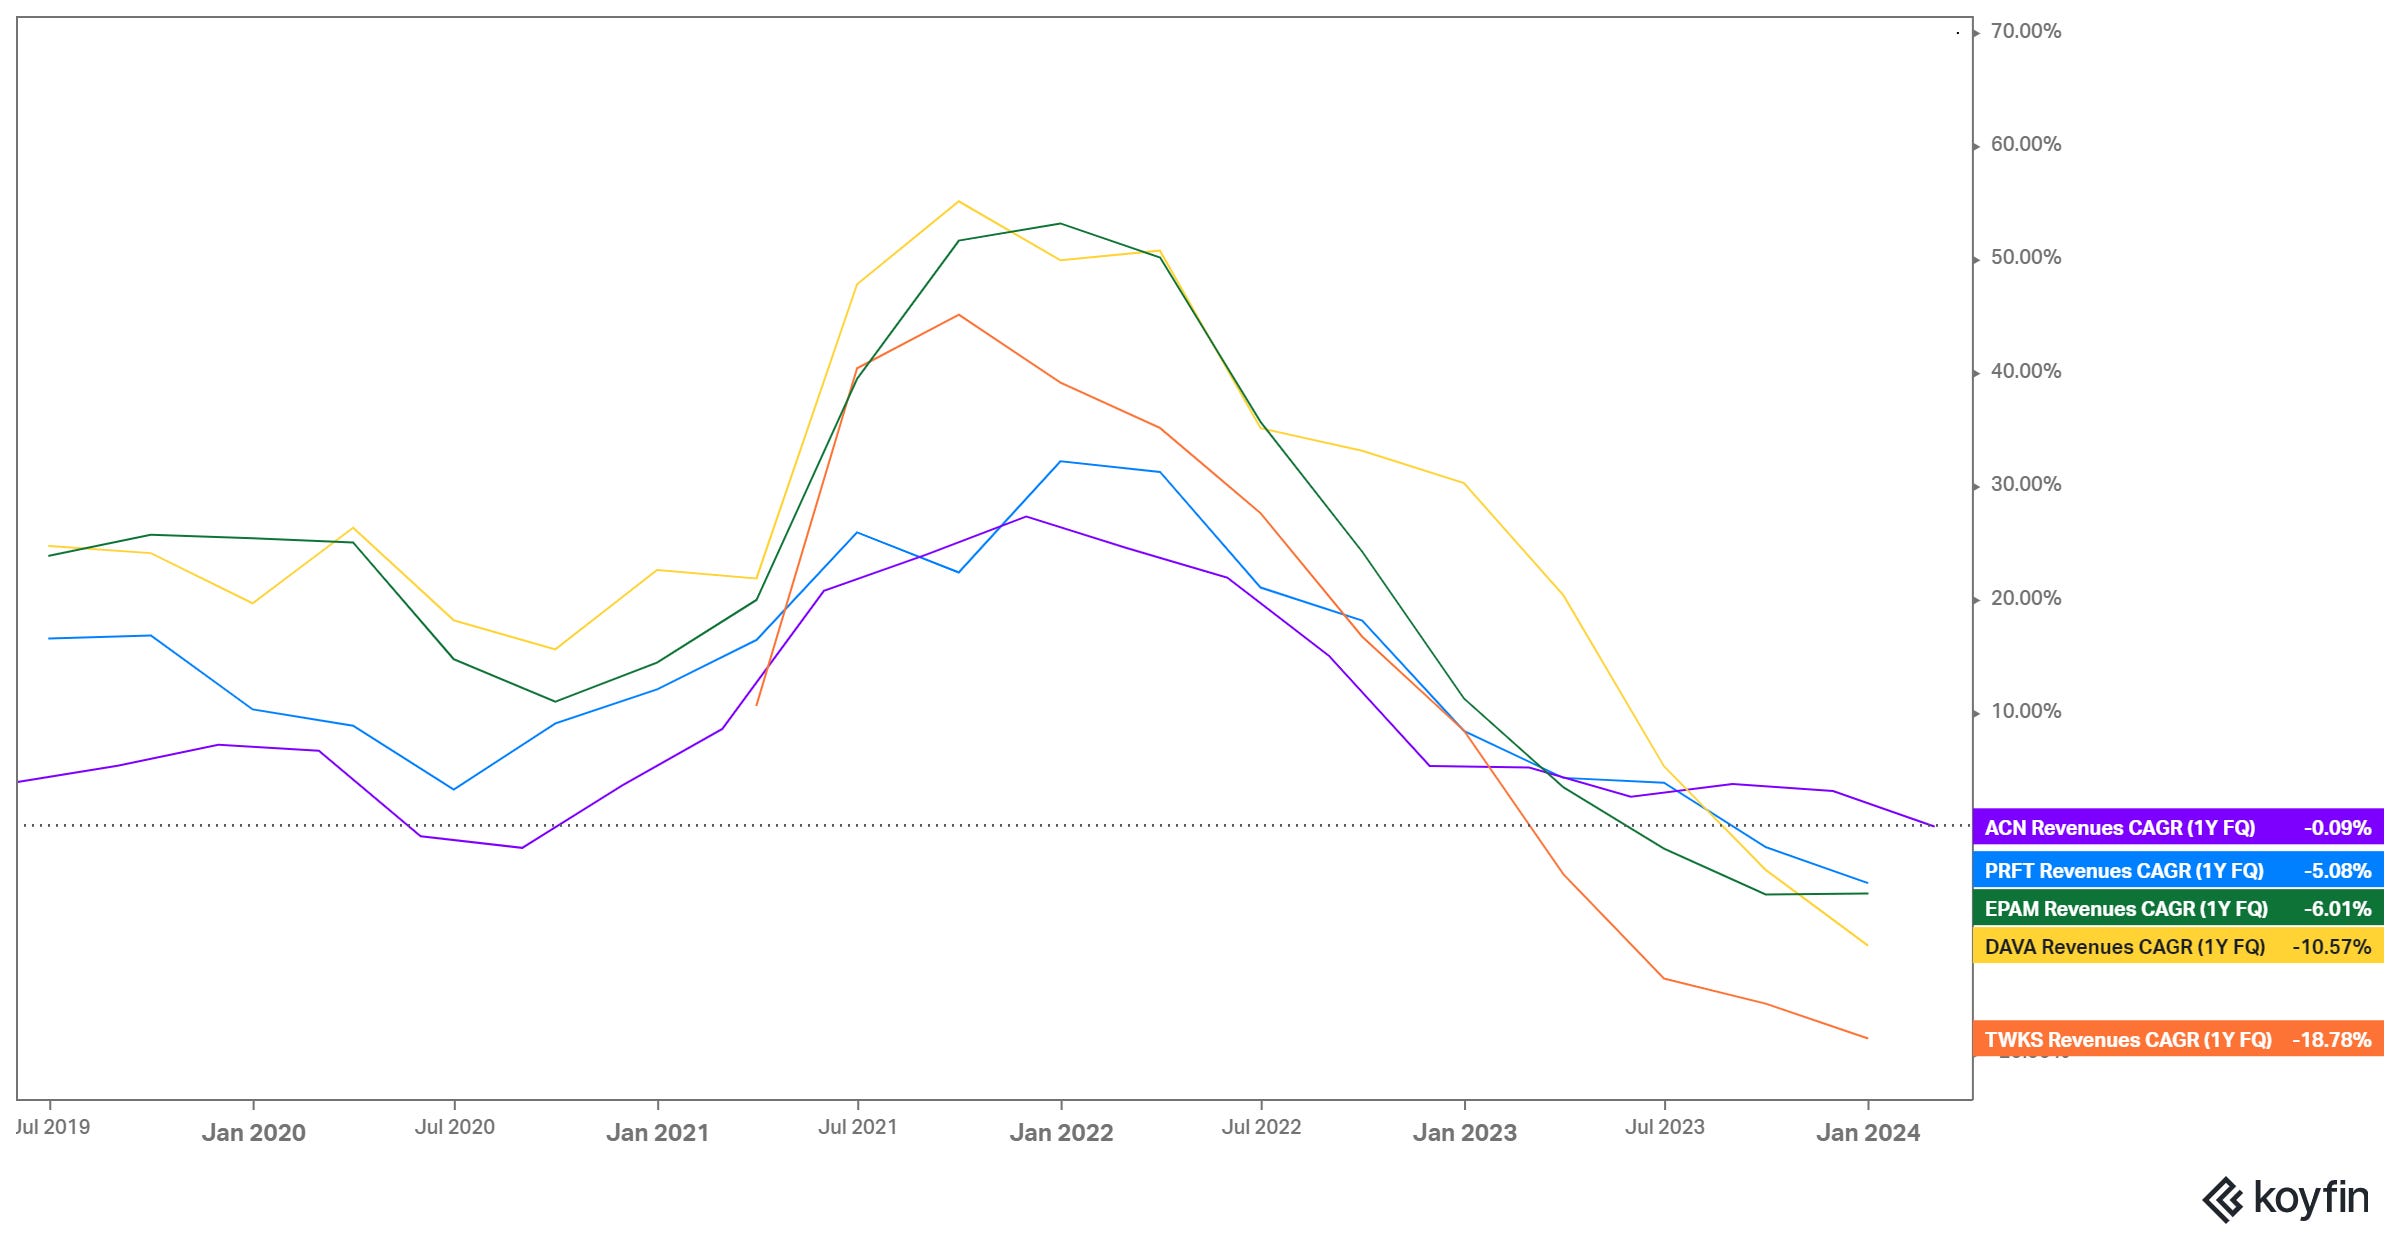
There seems to be a relatively obvious answer. Simply put, the cycle has turned:
source: Koyfin; year-over-year revenue growth rates by quarter
The trajectory of the industry seems logical. Organizations raced to consulting firms in 2021 as they developed remote work policies, managed device security, altered go-to-market processes, and made the other myriad changes required in the post-pandemic environment. Then in 2023 — the “Year of Efficiency”, as Meta Platforms META 0.00%↑ founder and chief executive officer Mark Zuckerberg termed it — organizations pulled back on spending of all kinds. Consultants likely took a bigger hit, because the major, critical initiatives of 2021-2022 had been completed (and because year-prior comparisons had become exceptionally difficult).
The problem with this explanation seems to be performance. The big leg down in the group year-to-date4 appears driven by investor disappointment in the fact that revenue and bookings aren’t recovering even as customer spend presumably normalizes5. That’s all the more true given that, again, it would seem like interest in generative AI should be spiking demand for Perficient and its rivals. In that context, investors are acting as if there is something wrong with the group long-term.
Except AI interest isn’t spiking demand, as executives across the industry are telling us. Here’s Accenture CEO Julie Sweet on her company’s Q2 conference call, when asked specifically why AI demand hadn’t increased spending in the sector:6
…it's about prioritization, right? So there’s [an] overall constraint on spending, right? So you make choices, right, as opposed to it being additive.
So they're not able to allocate extra budget. They're prioritizing their budget. So you're seeing more of a substitution right now as opposed to, "Hey, we need to do this. Let's add to the budget." And that's tied to the uncertain macro that's putting people constrained.
Here’s tech-focused outlet The Information describing a conversation with a consultant at KPMG:
Most large companies are finding the cost-benefit analysis of using AI tools “challenging” because of the high cost of the software and the difficulty of measuring productivity gains, Lohr said. Instead, large firms are usually drawing from their existing software budgets rather than devoting new money to slowly expand their AI usage, he said.
EPAM Systems EPAM 0.00%↑ CEO Arkadiy Dobkin said after Q3 regarding genAI that “the direct impact on the revenue is not going to be there yet”. On the Q4 call in mid-February, he cited the commencement of several hundred genAI projects but also noted that they were “relatively small”. Later in the call, he added that client genAI projects were “still…at this point a lot of experimentation”.
Endava chief financial officer Mark Thurston told a similar story from a different angle:
…some of our clients have said, "We don't want to use it [generative AI] at all," because they're worried about IP issues or regulation. Others are more open to it and are open to using it in a selective way. So from a productivity perspective, we're going to sort of pilot it and see how it plays and then what the wider sort of adoption of it will be.
We could add more quotes, but the important point is that the entire industry is saying basically the same thing: macro considerations are pressuring near-term revenue, and customers are not yet ready for the major genAI deployments.
The Fundamental Case for PRFT
That means two important things for PRFT (and most of its peers). First, the issue in recent performance is not related to market share. It’s possible that private giants Deloitte and KPMG are simply scooping up all the AI work, but the far more likely explanation is that there just isn’t that much work yet. Given the consistency of macro discussions — and a similarly consistent view that the business will start to turn somewhere between the second half of this year and the beginning of 2025 — this certainly sounds like an industry-wide problem, not a Perficient-specific one.
The second takeaway is that Perficient is actually running at trough earnings, rather than mid-cycle earnings. And in that case, the 35% YTD sell-off has moved the stock from being attractive to being compelling7. Shares trade at less than 9x EBITDA, ~10x 2023 free cash flow, and barely 10x the midpoint of 2024 adjusted earnings per share guidance. Even adding back stock-based comp, the stock is barely at 12x EPS (the normalized P/FCF multiple should be modestly better)8.
These are multiples well below the stock’s historical range. They’re not driven by leverage, either: net debt based on 2024 guidance is in the range of 1.4x EBITDA. More broadly speaking, this is a business that was a pretty good business for a couple of decades, a great business for a few years, and now has seen its cycle turn. ~12x earnings and free cash flow at the bottom is pretty obviously an enormously attractive multiple for that kind of business.
That’s particularly true given that AI demand is likely to drive growth at some point, if not necessarily in 2024. Indeed, as executives at Perficient and other firms have noted, many companies need to do significant work simply to get ready for AI. Whether it’s shifting to the cloud or getting data analytics in order, a large number of potential clients don’t actually have the foundation to develop genAI applications.
That of course is yet another reason why the trend hasn’t helped the industry, but looking forward it’s another reason why the likes of Perficient are set up for a potentially steep cyclical upswing. That upswing simply isn’t priced into PRFT at this point. In fact, in terms of growth basically nothing is priced in.
It leaves a relatively simple path to upside here, with two- to four-year earnings growth driving EPS up past $6 (bear in mind that Perficient, at least as of Q4, expects double-digit revenue growth in 2025) and P/E and P/FCF multiples returning to mid- to high-teen levels. It’s not unreasonable to see PRFT being a $100 stock once the cycle turns and sentiment changes, and that’s ~130% upside from Friday’s close.
Does It Have To Be PRFT?
Admittedly, if our thesis for PRFT is correct, then similar bull cases exist throughout the sector. And so it’s worth looking briefly around the group at potential alternatives.
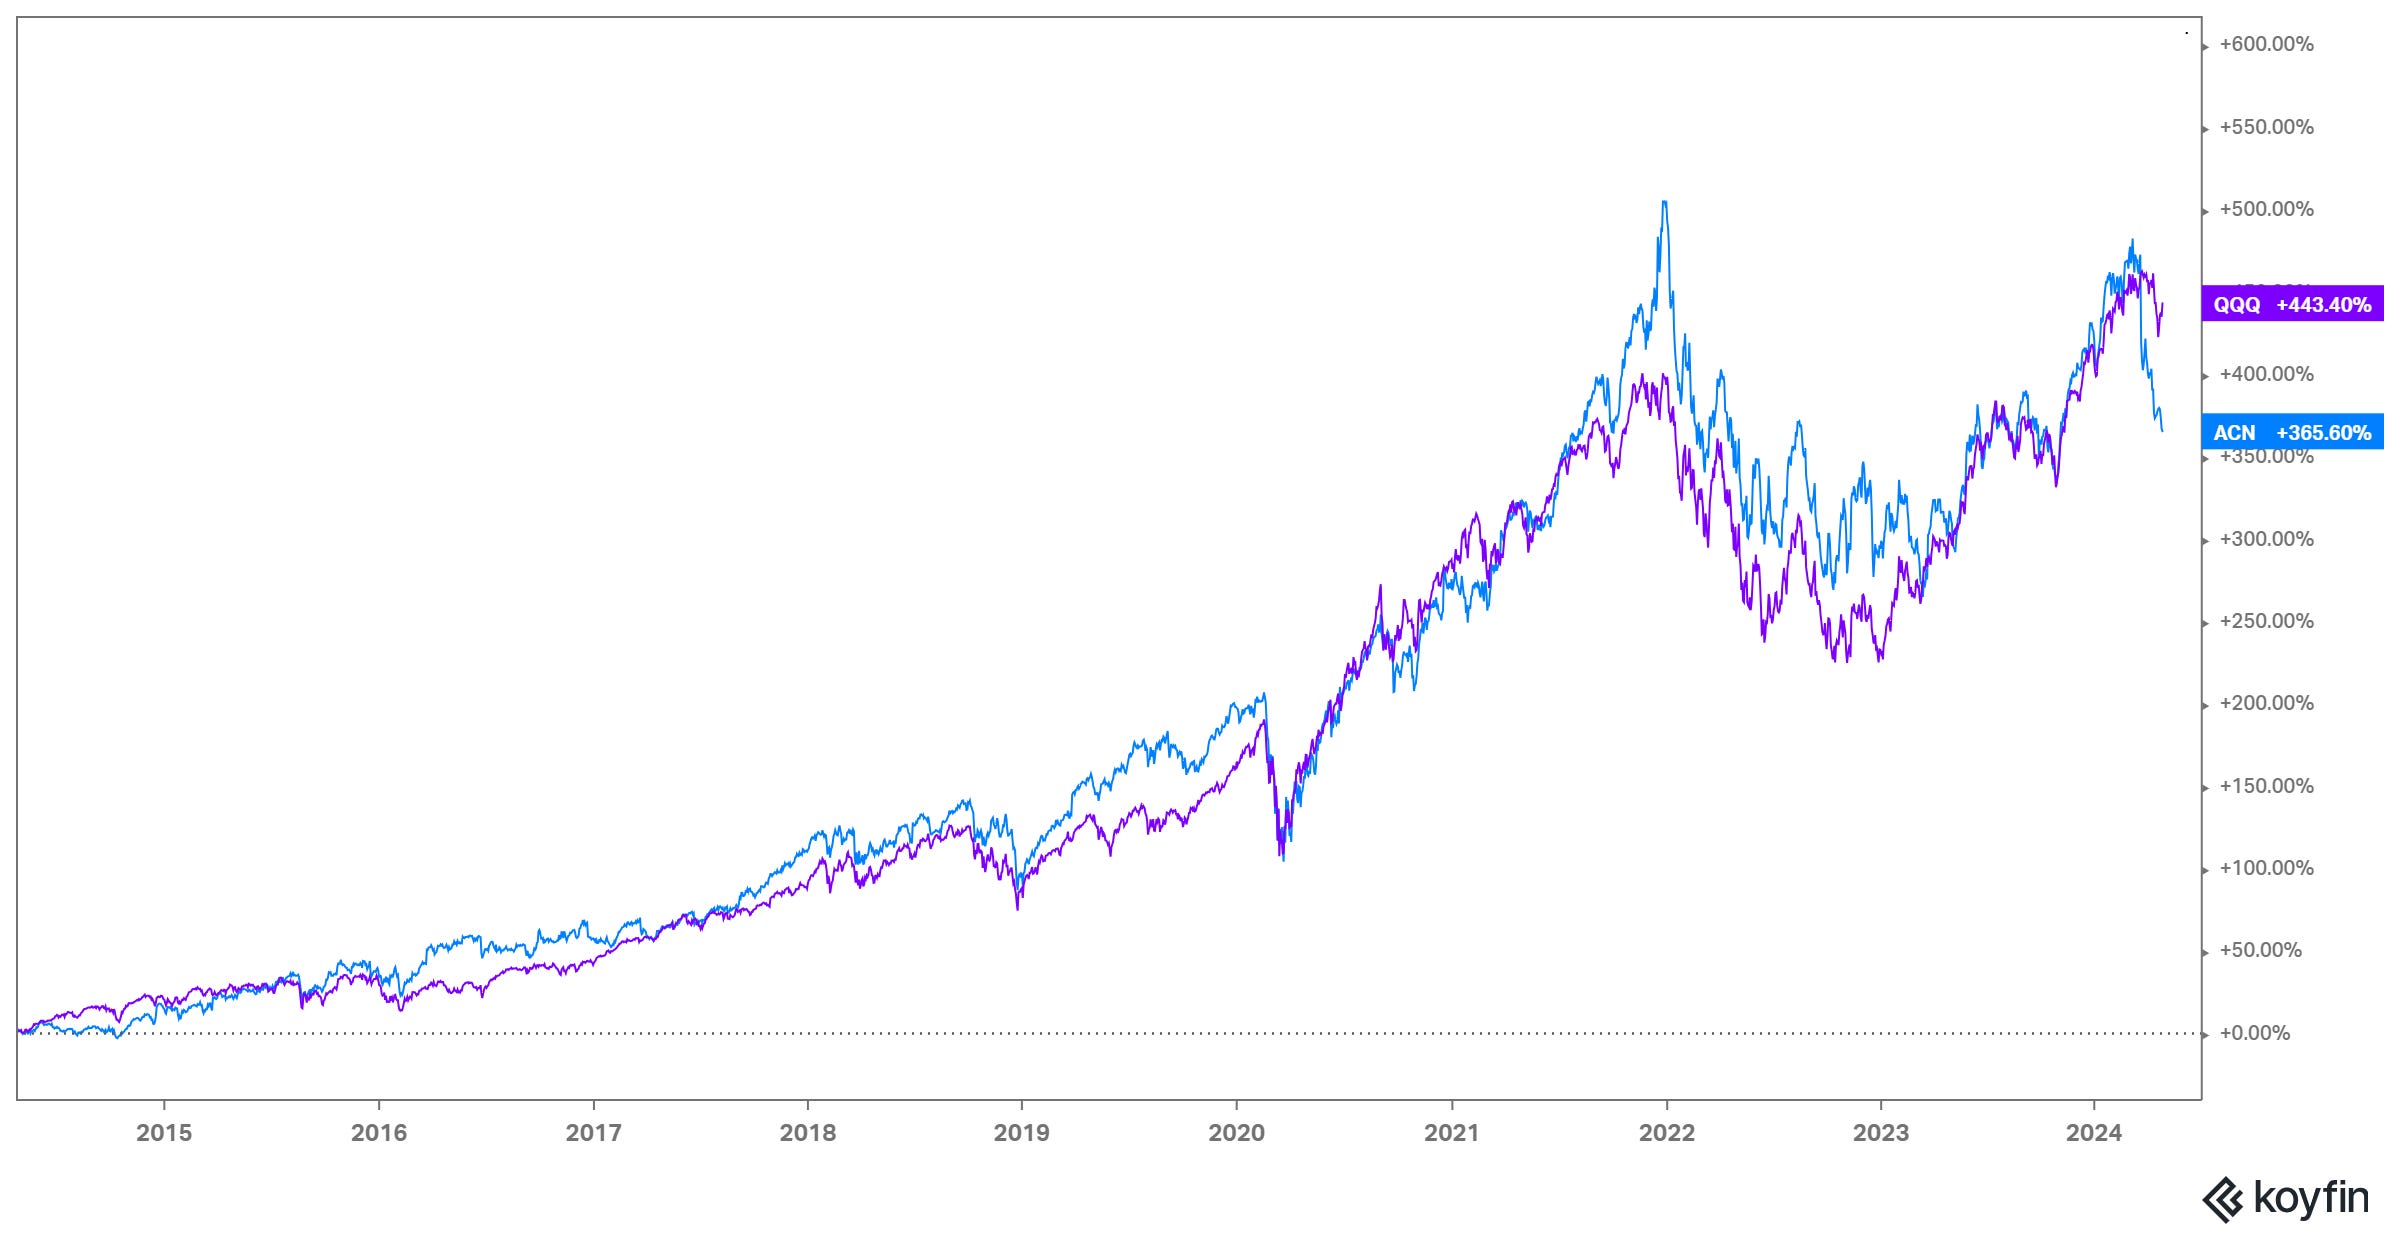
To be sure, we’re not opposed to simply buying a basket of these names. ACN at a 20% discount looks attractive given its long-running ability to track the NASDAQ 100 (no mean feat given that index’s performance). The correlation between ACN and QQQ suddenly has broken down in a way it hasn’t in years:
source: Koyfin
Accenture actually has talked up some strength in AI bookings (though they were still less than 3% of the company’s total in fiscal Q2) and is likely to benefit from the trend in some way. The broad strategy of simply buying a good business when the market panics9 appears to apply here.
Endava is an interesting contrarian play, though PRFT’s multiples look better. Thoughtworks is a name we’ve looked at closely, and TWKS is the highest-risk and highest-reward play in the group.
Notably, less than a year ago TWKS jumped to nearly $8 after a Bloomberg report that Apax Partners, its former private equity sponsor, was in serious talks to buy the company. The stock closed at $2.39 on Friday.
Of course, that’s not necessarily good news. It’s exceptionally difficult to take a $5 per share offer to shareholders when $8 seemingly was on the table a year ago. It’s even more difficult given that Thoughtworks’ IPO priced at $21 in September 2021. Debt is a moderate concern, but the bigger issue is that something seems wrong there.
Conference calls sound awful, Glassdoor reviews describe a collapsing culture, and the company is badly underperforming peers (again, consecutive years of 10%-plus declines in revenue; Perficient’s top line is expected to be relatively stable). Valuation isn’t that attractive, either: TWKS’ EV/EBITDA multiple is higher than Perficient’s.
The likes of EPAM, Globant S.A. GLOB 0.00%↑ and Cognizant Technology Solutions CTSH 0.00%↑ too can benefit.
Still, PRFT looks like the best option. It has generally the most attractive valuation, a long history of serving customers managing major tech trends, and decent performance given the external environment.
The chart is ugly, and Q1 earnings are a risk. But the play here is longer-term. At some point, the cycle is going to turn in Perficient’s favor. It seems like a good move to own the stock ahead of that point — even if doing so means being a little early.
As of this writing, Vince Martin is long PRFT. He may add to this position or acquire other stocks mentioned in the near future, particularly before or after Perficient earnings next week.
Disclaimer: The information in this newsletter is not and should not be construed as investment advice. Overlooked Alpha is for information, entertainment purposes only. Contributors are not registered financial advisors and do not purport to tell or recommend which securities customers should buy or sell for themselves. We strive to provide accurate analysis but mistakes and errors do occur. No warranty is made to the accuracy, completeness or correctness of the information provided. The information in the publication may become outdated and there is no obligation to update any such information. Past performance is not a guide to future performance, future returns are not guaranteed, and a loss of original capital may occur. Contributors may hold or acquire securities covered in this publication, and may purchase or sell such securities at any time, including security positions that are inconsistent or contrary to positions mentioned in this publication, all without prior notice to any of the subscribers to this publication. Investors should make their own decisions regarding the prospects of any company discussed herein based on such investors’ own review of publicly available information and should not rely on the information contained herein.
It’s a little weird to cite an email from Robinhood, admittedly, but I’m on the email list after due diligence on our recommendation of HOOD last year and it is a well-done chart.
The one-year chart is particularly useful here because it begins about four weeks before the blowout Q1 FY24 report from Nvidia NVDA 0.00%↑ in May 2023, which we’ve previously argued brought genAI completely, and permanently, into equity analysis.
There were two big long-term winners from that year’s crop: Nvidia NVDA 0.00%↑ and Booking Holdings BKNG 0.00%↑, which went public as Priceline.com and saw its stock rise 900% in the first month.
ACN -12%, DAVA -62%, EPAM -20%, PRFT -35%, TWKS -50%.
This is probably more true for a firm like Perficient, which wasn’t nearly as exposed to the belt-tightening in tech as companies in the sector pivoted from a focus on growth to a focus on profit margins.
h/t Portsea Capital for the first two quotes here.
To that point, we first started working on this idea back in February, when PRFT traded 60% higher; it was largely short-term worries about the chart and earnings, rather than valuation concerns, that held us back from recommending the stock at the time.
Market cap at Friday’s close is $1.47 billion, excluding from the diluted share count the impact of convertible debt (nearly all of which matures in 2026 with a current conversion price of $191; Perficient still calculates diluted shares on an as-converted basis). Net debt is $268 million, for an enterprise value of $1.74 billion.
2024 Adjusted EBITDA, based on guidance, should be in the range of $200 million. Adjusted EPS is expected to be $4.05-$4.20. ~$30 million in stock-based comp (up from $27M-plus in 2023) at a 28.5% tax rate (based on guidance) is a ~$0.62 per share boost to the adjusted figure, leaving ‘true’ adjusted EPS around $3.50.
And yes, we’d argue that a 20% decline in response to that earnings report qualifies as “panicking”.
Congratulations, well done and thank you, Overlooked Alpha. What a sensationally great call!