

On its face, internet browser business Opera Limited OPRA 0.00%↑ looks like an easy buy. Shares trade at a little over 10x EBITDA despite impressive growth and profitability.
With one quarter left in the year, Opera is guiding for revenue to increase 19% year-over-year, with full-year Adjusted EBITDA margins of 24%. Leverage is not an issue: Opera actually has no debt, with cash and investments carried at $360 million.
Underpinning those fundamentals is an attractive business. Opera’s web browser obviously competes with giants Alphabet and Microsoft, but the company has carved out a solid, if small, niche in the space. A host of features and the launch of a gaming-focused browser have solidified that niche and driven recent growth. Even management looks solid: investments in a karaoke app and an entrance into emerging market fintech both were exited at gains, and a payment business in Africa appears to be growing nicely.
Not All Good
At the same time, there are some real questions. Even though the business is headquartered in Norway, Opera Limited is a Cayman Islands-incorporated company that is majority-controlled by a Chinese private equity firm. Accusations of self-dealing, including those raised by Hindenburg Research back in 2020, have dogged the stock.
And while bulls point to a strong niche in the browser space, Opera’s share remains small, at less than 3% worldwide. Notably, that share has declined over time. So Opera’s top and bottom-line growth has come despite share losses, leaving the business possibly exposed to a plateau in a key metric.
Meanwhile, the stock itself has been a rollercoaster ride, no doubt amplified by the low float:

source: Koyfin
How We Got Here
Opera’s first browser publicly launched in 1995, a year after Netscape and roughly concurrent with Microsoft’s release of Internet Explorer. Opera was originally “trialware”, requiring a purchase after an initial period, but the company switched to ad-based monetization in 2000. Five years later, ads were removed, and a partnership with Google, the default search engine, became the primary source of revenue (it still is; Google accounted for 42% of revenue in 2023). In 2002, Opera launched the first browser for smartphones, and an Android browser launched in 2013 remains a key product today.
source: Opera
In 2016, Opera planned to sell its entire business — which also included app and game development and a mobile ad platform — to a Chinese consortium. But the deal was blocked by regulators, and so only the browser business was acquired1. Two years later, Opera went public again — but not as a public equity exit. Chairman James Yahui Zhou, via a pair of firms, still owns 72% of the company, even after selling a slug in a secondary offering in December.
Zhou’s ownership has brought scrutiny to the company. In 2020, well-known activist short seller Hindenburg Research took aim at Opera, citing questionable investments in companies owned by Zhou. Among them was a $30 million investment in Starmaker, the developer of a karaoke app targeting users in developing countries. Hindenburg also cited questionable lending practices at a fintech business Opera was developing.
But in retrospect, Zhou’s use of capital has paid off. Starmaker (later renamed Star X) was divested for $83.5 million. The fintech business was rolled into an asset that too was sold for a profit. Opera even launched what it called an “investment program” which, unusually, included short positions. The program generated returns of $26 million over four years before being discontinued last year. Opera has been quite good at buying its own stock as well: in 2022, the company bought back 23.375 million American Depositary Shares2 at $5.50 in a single deal with a pre-IPO shareholder. Open market purchases that year and the following totaled $50 million at an average cost per ADS just above $8. There’s even a 4.6% dividend yield at this point.
And so bulls might argue that OPRA isn’t nearly as speculative as it was two years ago. A Cayman-based company controlled by a Chinese PE firm, making investments into businesses owned by its chairman and shorting stocks, sounds almost by definition speculative. But the strategic shift away from that profile — and it was a strategic shift — to a more focused, more simple, story has increased investor confidence and driven multiple expansion. (OPRA’s EV/EBITDA multiple has in fact about doubled.) Add growth to the mix and the rally should continue.
Focusing On The West
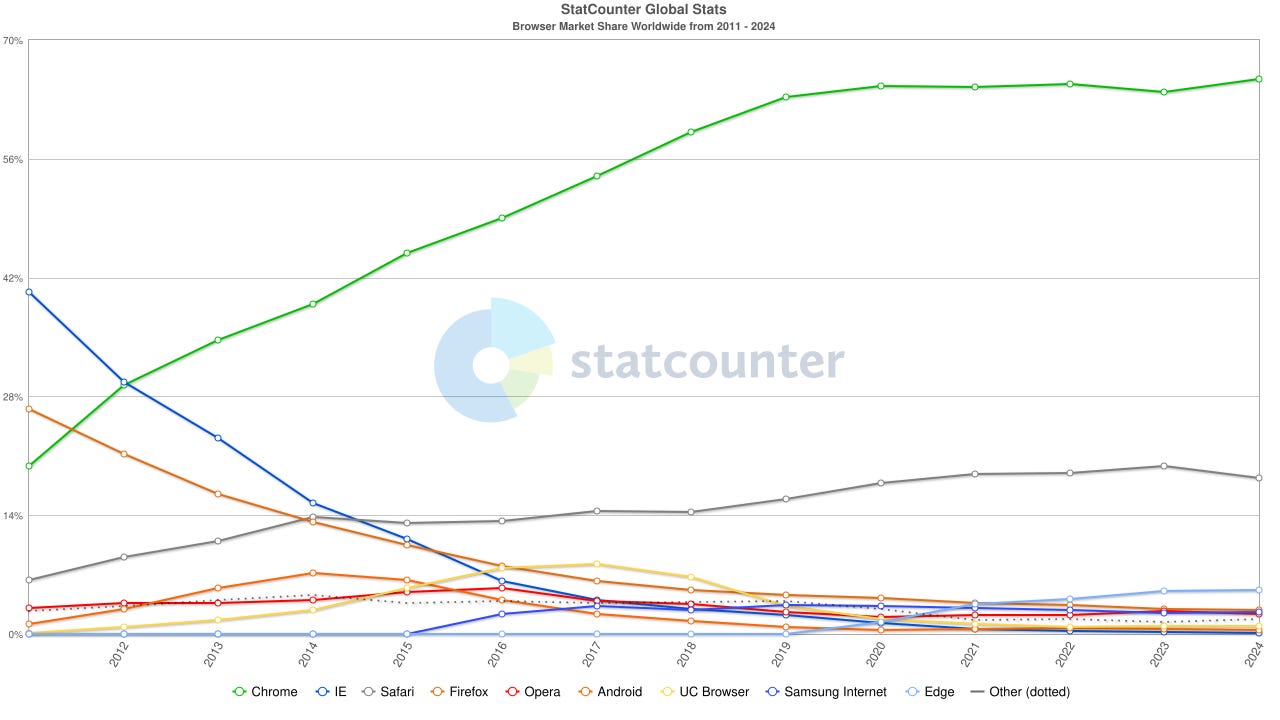
Still, Opera remains a relatively small player in a browser market increasingly (and impressively) dominated by Google:
source: StatCounter
Opera’s market share in October, per StatCounter, was just 2.2%, behind other small rivals like Microsoft Edge (5.25%) and Firefox (2.65%). Notably, that share is down rather sharply. As recently as 2016, Opera had over 5% of the market.
Indeed, Opera’s own figures show a decline. In the fourth quarter of 2015, the company had 340 million monthly browser users3. In Q3 2024, the figure was 296 million. That’s a 13% decline during in which the total number of browser users has increased globally, particularly on the mobile side which was Opera’s strength during the 2010s.
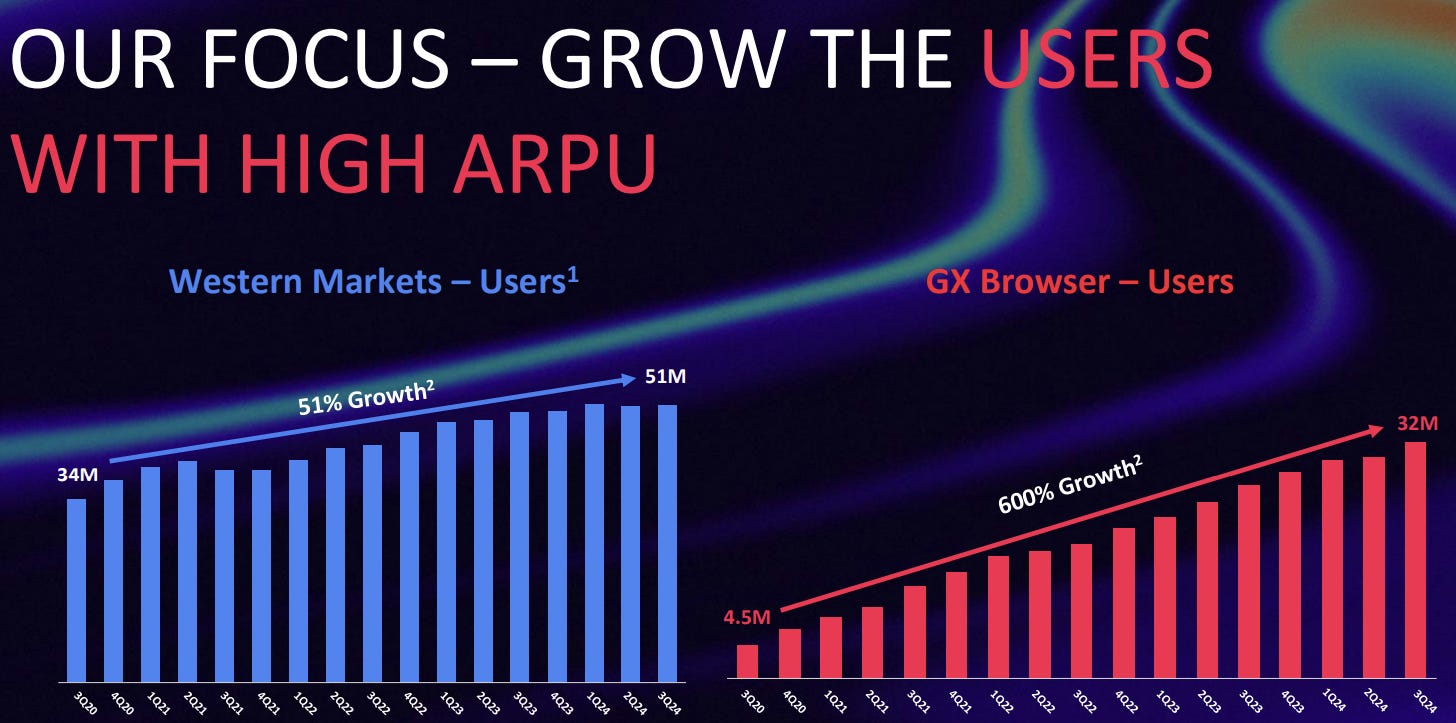
The declines in users and in market share seem like bad news. But they are a result of a shift in business strategy executed alongside the changes in corporate strategy. Opera has pivoted toward more Western markets, which offer better monetization and higher ARPU (average revenue per user). And that strategy seems to be working in terms of reach:
source: Opera investor presentation, Q3 2024
Opera GX is the company’s gaming browser, which as the chart above shows has been a hit since its release in 2019. The shift to Western users, meanwhile, is notable. When Opera first went private in 2016, its base was in Africa, where it was the most popular browser on the continent. Southeast Asia was another region of focus.
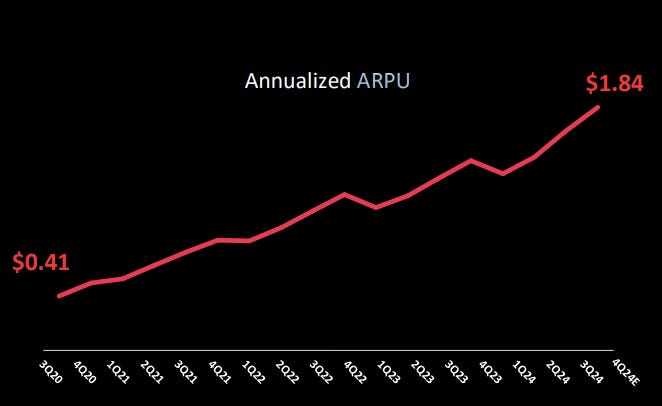
The West still makes up a small part of the user base — 17% as of Q3 — but the figure is growing. That, along with GX (which provides better monetization, notably through targeted advertising) has led ARPU to soar:
source: Opera investor presentation, Q3 2024
And so the loss of users, from Opera’s perspective, is not really a problem. As chief financial officer Frode Jacobsen put it on the Q3 2023 conference call, “The rotation of our user base has low monetized users churning out and higher monetized users coming in.”
With the launch of new products, such as the Aria AI assistant and Opera News, this trend should continue. ARPU at Opera GX is double what it is for Opera as a whole. Aria — which drove some AI-related optimism toward OPRA last year — still has room to be a revenue center, instead of simply a browser feature.
The success of the pivot toward Western markets suggests further room for ARPU expansion going forward — and thus continued revenue growth. Qualitatively, it also seems to dispel the management concerns that dogged the stock in the past. Hindenburg’s 2020 short report wasn’t necessarily wrong, but many of the factors that the short seller highlighted simply don’t exist any more.
There aren’t weird investments and related-party transactions. Instead, there’s a seemingly well-run (if still controlled) company that is posting impressive growth and returning capital to shareholders. Yet the valuation assigned to OPRA doesn’t seem to reflect that profile. It looks, instead, like some of the old worries are keeping the stock’s valuation relatively low.
OPRA To $25
At Thursday’s close of $18.17, Opera has a market cap of $1.63 billion. There’s $106 million in cash on the balance sheet, and no debt — plus an investment in OPay currently carried at $253 million.
Using that carrying value, Opera has an enterprise value of $1.27 billion. That’s just over 11x the midpoint of Adjusted EBITDA guidance ($112-$114 million) — and given that Opera has hiked its outlook three times already in 2024, investors likely can model actual results above the high end of that range. P/E sits below 20x, and adjusted for cash (and interest income) is in the ~17x range based on 2024 results.
Given the fundamental profile, those multiples seem far too cheap, particularly for a stock with a potential AI tailwind. There’s some upside from OPay as well: the stake was revalued last year, and in May OPay announced that it had generated its first monthly profit4. Opera has said that at some point, it will divest that investment, with proceeds likely going to shareholders as a special dividend.
If anything, OPRA at $18 looks perhaps better than it did at $5. It was relatively easy to pass on the stock the because of the perception around some of the investments and corporate governance. With the story for investors so much simpler and stronger, and the business clearly firing on all cylinders (even growing through the advertising pullback seen in 2022-2023), the risks seem so much lower. Yet the rewards are still quite evident.
Multiple expansion to the mid-20s on a P/E basis (plus cash and OPay) or mid-teens on an EV/EBITDA basis both suggest a double if Opera keeps growing its bottom line at a 10%-plus clip. Given momentum behind GX, the pivot toward higher-value Western users, and the potential benefits of Aria, Opera News, and other efforts, that outlook hardly seems aggressive.
The ARPU Question
And yet, the market still doesn’t seem to be giving OPRA the credit it deserves. One potential explanation is that legacy worries about the corporate structure still color the perception of the stock. Another is that investors might be worried about the sustainability of the growth over the past few years.
After all, ARPU presumably can’t grow at the current rate for much longer: as the graph above shows, it’s more than quadrupled in four years. And while it’s easy to argue that further penetration of Western users can keep that trend intact, it’s also much more difficult to acquire those users. Google’s dominance alone is an impediment, and Microsoft has in recent years emphasized growth in Edge. Opera’s browser does seem to be a legitimately competitive product5, but in consumer tech, size and branding often prove more important than quality.
Opera’s own history provides a bit of caution as well. After the 2018 IPO, the company’s focus was not on the West, but almost solely on emerging markets in Africa and Southeast Asia. On the company’s very first conference call, co-chief executive officer Song Lin said that Africa was Opera’s “most important” market. After Q1 2019, he told listeners:
Africa and several emerging Asian markets represent a significant multiyear opportunity and we have a leading position and have driven strong growth over the last year. We think this is just the beginning and there is a real opportunity to build upon our leadership positions.
Five years later, Lin explained declines in monthly active users as a result of a focus on “quality over quantity”. In other words, the African MAUs that underpinned the strategy in 2019 were, in 2024, essentially disposable.
To be sure, that doesn’t mean the strategy is wrong now, or was necessarily wrong then. But the strategy of 2019 essentially ran its course, at which point Opera had to find a new source of growth in Western markets. Presumably, history will repeat: Opera will hit something of a ceiling in its Western user base (barring significant share gains from Google and Microsoft) and its ability to monetize those users. Management has said that Western users are ~8x more valuable than those in emerging markets. Given that ARPU is already up more than 300%, that does suggest the benefits from geographic shift are likely to slow at some point in the near future.
That in turn means that, at some point, Opera’s user base needs to start growing again. It may do so: in Europe, the company should benefit from a decision by Apple to allow default apps including Safari to be deleted. GX seems to be an excellent product with a clear target market, and could take incremental share in the Americas. Aria can further strengthen the product (though it’s not as if Google and Microsoft are standing still in terms of AI).
As good as the numbers look, there’s still some reason to be cautious that current growth rates aren’t necessarily sustainable. Increasing ARPU can’t drive growth in revenue, or upside in the stock, forever. History suggests that number will eventually flatten out and that’s a problem in forward-looking markets. So there has to be some belief in the product and the ability to regain market share from rivals. If Opera can hang on to even a small amount of growth then OPRA stock can continue to climb.
As of this writing, Vince Martin has no positions in any securities mentioned.
Disclaimer: The information in this newsletter is not and should not be construed as investment advice. Overlooked Alpha is for information, entertainment purposes only. Contributors are not registered financial advisors and do not purport to tell or recommend which securities customers should buy or sell for themselves. We strive to provide accurate analysis but mistakes and errors do occur. No warranty is made to the accuracy, completeness or correctness of the information provided. The information in the publication may become outdated and there is no obligation to update any such information. Past performance is not a guide to future performance, future returns are not guaranteed, and a loss of original capital may occur. Contributors may hold or acquire securities covered in this publication, and may purchase or sell such securities at any time, including security positions that are inconsistent or contrary to positions mentioned in this publication, all without prior notice to any of the subscribers to this publication. Investors should make their own decisions regarding the prospects of any company discussed herein based on such investors’ own review of publicly available information and should not rely on the information contained herein.
The remaining business was renamed Otello, and is still publicly traded on the Oslo Stock Exchange under the ticker ‘Otello’. Shares are at an all-time low.
The security listed in the U.S. is the ADS, which represents two ordinary shares.
281 million on mobile, 59 million on desktop.
That news also mitigates one source of modest potential downside. Part of Opera’s stake in OPay was created in exchange for the Asian operations of Nanobank, a former Opera subsidiary. The preferred shares received can be forfeited if the acquired business disappoints, based on cumulative performance across 2023 and 2024. Per the 20-F, the value of those shares is a bit under $100 million, or ~6% of Opera’s current market cap.
Reviews seem to cut both ways; even for GX, some Opera users cite massively improved performance with lower CPU workloads, while others have the exact opposite experience. It does seem like Opera’s users tend to swear by the product.