
Highlights:
Grab Holdings, the “Uber of Southeast Asia” has been dead money for two years, even as peers rally.
There’s an intriguing argument that the bull case for GRAB is hidden by losses in its financial services division.
Whether that case needs to be bought now is up for debate; Grab clearly still has work to do in gaining investor confidence.
AerSale’s ugly Q4 report decimates the bull case. A new one can be built, but it’s not likely to arrive soon.
Grab Holdings beat Uber in Southeast Asia. That’s mid-2010’s Uber, the most valuable startup ever, backed with billions of dollars in capital and with access to tens of billions more. The two companies had a price war in several markets, and it was Uber that capitulated. In a 2018 deal, Uber took 27.5% of Grab (its stake is now about half as much) plus a board seat (which remains occupied by Uber chief executive officer Dara Khosrowshahi).
At Thursday’s close, Grab has a fully-diluted market capitalization of $12.5 billion, and an enterprise value just above $7 billion. Relative to more recent marks, that valuation looks like a disappointment.
GRAB is down 68% from the $10 price at which it merged with a SPAC (special purpose acquisition company) in 2021. But that merger was executed at an enterprise value over $30 billion, and, we believe, the highest valuation ever in a SPAC deal.
The multi-year performance of the equity isn’t exactly inspiring, yet this is a much larger, business than it was six years ago. The market doesn’t seem to care: both Uber and its rival Lyft have rallied nicely of late, while GRAB has been left behind.
It’s hard not to wonder whether GRAB might be the next one to rally.

source: Koyfin (one-year chart)
How Grab Got Here
In 2011, Harvard Business School classmates Anthony Tan and Tan Hooi Ling won second place in an HBS New Venture competition. Using the $25,000 prize money, they launched MyTeksi, an app for booking taxis in Malaysia (the company has since moved its headquarters to Singapore). The next year, the name was changed to GrabTaxi.
GrabTaxi quickly expanded geographically (it now operates in eight countries) and into new end markets. In 2014, the company entered the ride-hailing market with GrabCar. It also launched GrabBike, for motorcycle taxi rides. The next year, GrabExpress marked the company’s move into deliveries. Food and grocery delivery followed. In 2017, the company (now known just as Grab) moved into financial services. Those operations now include a full-on digital banking business and the OVO digital wallet.
What Grab is now is a “superapp” (the company actually uses that term itself), along the lines of China’s WeChat or what Elon Musk envisions for X:

source: Grab Investor Day presentation, 2022
Grab operates in eight countries1 in Southeast Asia, and now serves over 500 cities. It is, per multiple sources, the leading business in the region in both food delivery and ride-hailing.
In 2023, more than half of Grab’s GMV2 and revenue (~$21 billion and ~$2.4 billion, respectively) came from Malaysia and Singapore, with total distribution as follows across its segments:
Deliveries: 50.6% of revenue; 48.5% of GMV
Mobility: 36.8% of revenue; 25.8% of GMV
Financial Services: 7.8% of revenue; 24.7% of GMV
Enterprise And New Initiatives3: 4.7% of revenue; 1.0% of GMV
Hiding In Plain Sight
Fundamentally, GRAB might be stronger than it looks. 2023 Adjusted EBITDA was negative $22 million. That was a huge improvement from a loss of nearly $800 million the year before. But like so many unprofitable growth companies, Grab last year focused on margins at the expense of top-line performance. It slashed incentives to boost revenue but at the cost of GMV, which rose just 5%. The bear case might be that this business doesn’t really grow without an incentive structure that makes profits unachievable.
But there is a drag on that performance from the financial services business, which posted a $294 million adjusted EBITDA loss last year. Adding that back, Grab would have generated over $270 million in Adjusted EBITDA in 2023. Guidance for 2024 on a consolidated basis projects $180-$200 million in Adjusted EBITDA. That’s probably ~$300-$350 million excluding further financial services losses4.
The Bull Case for GRAB
EV/EBITDA excluding financial services losses is in the low 20s, while UBER is at 28x, and LYFT 20x. Grab should grow 2024 revenue at roughly the same rate (its guidance is for 14%-17% growth, while the Street sees the two Western platforms growing ~16%), but ostensibly has a larger, longer opportunity.
Grab has less competition than does Lyft (a clear second to Uber). Its primary rival, PT GoTo Gojek Tokopedia (GOTO.IDX), known as ‘GoTo’, seems to be losing share (its GMV declined q/q in both Q1 and Q2 of 2023. That company reports Q4 numbers later this month), and its stock is down 81% over the past five years.
The Southeast Asia market as a whole is probably in the earlier innings of its digitization and adoption of ride-hailing and delivery services, meaning Grab has the potential to consolidate share of a market that, over a multi-year timeline, may well grow faster than those in developed economies.
That consolidation may come quicker than planned. Per Bloomberg, last month Grab and GoTo restarted discussions surrounding a merger. Whether that merger could get through regulators is uncertain: a much smaller acquisition has been held up in Singapore. But even the possibility of a dominant business in the region — which has nearly 700 million residents and in 2022 generated ~$3.6 trillion in gross domestic profit — seems like an attractive call option.
The balance sheet isn’t a risk, with net cash and investments of over $5 billion. In the Q4 release, Grab even announced a $500 million buyback, suggesting it is comfortable with cash burn in the coming years5. The business model is intriguing: the complementary nature of the various services — using banking to lend to rideshare drivers or cross-marketing between rideshare and delivery — would seem to add yet another tailwind to long-term growth. More broadly, this is a business that has existed in its current form for only about a decade. It will get better and more efficient (as has Uber).
The weakness in GRAB does seem a little weird. This seems like the kind of market where the stock should have found a bid at some point. Growth is back in fashion, Grab in 2023 proved its profit bona fides, and investors have been attracted to a number of similar plays. It’s not just UBER and LYFT that have roared but DoorDash and fellow Singapore resident Sea Limited SE 0.00%↑, which serves a similar geography.
If Uber is worth over $150 billion, is the “Uber of Southeast Asia” really worth just $7 billion?
Not A Buy — Yet
It’s certainly an intriguing case. But it’s tough to pound the table just yet. Revenue guidance for 2024 disappointed investors, sending GRAB lower. Competition includes publicly-traded ComfortDelGro (C52.SI) and remains enough of an issue to keep a lid on margins. Upstarts like Be Group in Vietnam (which just raised $30 million) and Taxi Maxim in Indonesia and Malaysia appear to be growing at solid rates. Foreign exchange is a risk (though Grab does report in U.S. dollars). So is the macroeconomic environment in southeast Asia.
There’s a clear lack of trust from the market, which is reflected in the fact that Grab expects to post a nearly $1 billion improvement in EBITDA in two years (2022 to 2024) and yet the stock hasn’t moved an inch.
The nature of platform businesses, as the 12-month performance of UBER and LYFT show, is that modest increases in revenue expectations can lead to much higher increases in profit forecasts and thus the share price. GRAB might be a name where it’s safer to buy a 15% post-earnings (or post-merger) rally than trying to time when and if sentiment will finally improve. But it’s definitely a name worth watching.
AerSale Crashes
In our August piece on AerSale ASLE 0.00%↑, we spent a good deal of time covering the risks, and those risks have played out. ASLE is almost certain to hit an all-time low on Thursday after a disastrous fourth quarter report.
Here’s how Q4 played out relative to implied guidance for the quarter based on full-year guidance updated after the third quarter:
Revenue: $94.4 million versus $160-$180 million
Adjusted EBITDA: $6.0 million versus $33.7-$38.7 million
Management’s argument is that equipment sales slipped out of the quarter and into the first half of 2024. Those sales are rather lumpy, and so that explanation on its own has some credibility.
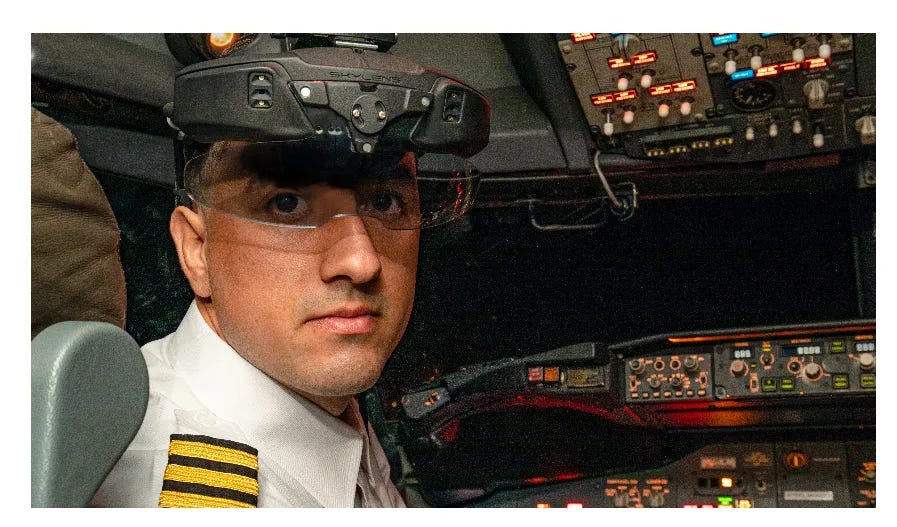
But AerSale also simply decided not to give guidance for this year, which strongly suggests that there’s a bigger risk than just timing to these deals. The bigger issue is on AerAware, an EVFS (Enhanced Vision Flight System) which management has pitched as a potentially transformative technology for pilots.
source: AerSale
Chief executive officer Nick Finazzo has long talked up the demand for the product. All the way back on the Q3 2022 call in November of that year, Finazzo projected that “we’ll soon bring AerAware to market with multiple launch customers.”
A lengthy certification by the Federal Aviation Administration, which finally arrived in December of last year, slowed the marketing process, but Finazzo said discussions continued, and on occasion pointed to nine-figure annual revenue from major orders. All that’s been accomplished four months after certification, per the Q4 release, is “five written proposals”.
A New Story Is Needed
Across the board, ASLE now looks like a mess. The balance sheet has taken a huge hit amid inventory build. Net cash was $147 million at the end of 2022; AerSale closed 2023 with net debt of nearly $32 million. It’s not at all clear what AerAware is worth, if anything; this is a business that bulls argued was worth at least $10 per share and yet has done nothing to this point.
The broader issue is that it’s not clear what this business actually is supposed to be. As we noted, AerSale was seeded with $250 million in capital in 2010 and told to make money by, essentially, trading airplanes and equipment. 14 years later, at the after-hours price, the business is worth ~$425 million, an annualized growth rate of under 4%. The idea that management here could create value in the market simply hasn’t worked out.
Unsurprisingly, Leonard Green & Partners, the P-E firm that led the major investment in 2010, continues to shrink its position. To be fair, the end of life for its funds is probably at play, but in retrospect a 4 million share secondary offering in December (a week after AerAware’s certification) was a clearly negative tell.
The question is if there is ability to salvage value here. At the after-hours price, ASLE is trading right at tangible book value, which for an asset-heavy business does mean something. The negative free cash flow in 2023 was driven almost solely by a huge inventory build ($169 million), which will reverse as that equipment eventually is sold.
AerAware maybe isn’t a zero. The upheaval in the aerospace industry driven by Boeing BA 0.00%↑ and Spirit AeroSystems SPR 0.00%↑ should create opportunities over time.
The problem is that investors simply can’t trust that current management will take advantage of those opportunities. One co-founder already retired at the end of 2023; it would be a surprise if Finazzo doesn’t do the same by the end of 2024, perhaps with some prodding from LGP.
There is room for a turnaround narrative to take hold here — but that narrative isn’t arriving immediately. In the meantime, the old narrative seems completely negated. This was supposed to be a business benefiting from inventory reduction, cyclical tailwinds, and growth in new products. None of those three pillars of the bull case have held.
We’ve had success in aerospace with a solid read on SPR’s movements, and we still like Astronics ATRO 0.00%↑, which we recommended in January ahead of an excellent Q4 report last month. That’s a business that has shown it can benefit from industry growth. AerSale no longer can say the same.
As of this writing, Vince Martin is long shares of Astronics.
Disclaimer: The information in this newsletter is not and should not be construed as investment advice. Overlooked Alpha is for information, entertainment purposes only. Contributors are not registered financial advisors and do not purport to tell or recommend which securities customers should buy or sell for themselves. We strive to provide accurate analysis but mistakes and errors do occur. No warranty is made to the accuracy, completeness or correctness of the information provided. The information in the publication may become outdated and there is no obligation to update any such information. Past performance is not a guide to future performance, future returns are not guaranteed, and a loss of original capital may occur. Contributors may hold or acquire securities covered in this publication, and may purchase or sell such securities at any time, including security positions that are inconsistent or contrary to positions mentioned in this publication, all without prior notice to any of the subscribers to this publication. Investors should make their own decisions regarding the prospects of any company discussed herein based on such investors’ own review of publicly available information and should not rely on the information contained herein.
Cambodia, Indonesia, Malaysia, Myanmar, the Philippines, Singapore, Thailand and Vietnam.
Gross Merchandise Value, the total dollar value of transactions on the Grab platform.
Includes advertising, GrabMaps, and third-party partnerships.
Grab said after Q4 that losses in the segment have peaked, and would narrow sequentially across 2024. A target for 2026 profitability in the business remains intact; it’s a reasonable guess that Financial Services probably posts a $175-$200M loss this year on its way to $0 two years later.
That repurchase authorization does throw a bit of water on the merger speculation, however. Grab should want as much cash in the deal as possible, given it’s pretty difficult to argue that using stock as a currency is attractive at current levels. The strategy of buying back stock ahead of the merger and re-issuing it at a (hopefully) higher valuation seems somewhat unlikely for a company without a history of buybacks.
What's the investment case for ASLE to be worth less than book value?